Capitalist Communist Conundrum
Transparency, trust and what might come next
By Geoff Fane. Written with help from AI. The views are mine. 1 October 2026.
Are we living through late-stage capitalism, or is capitalism simply transforming again, as it did from industrial capitalism to the post-war mixed economy to the globalised, neoliberal model of the past forty years?
Neoliberalism was the bet that open trade, light regulation, privatisation and freely moving money would lift everyone. In some places it did; in others it moved the factories offshore and left towns behind. Even the World Trade Organization accepts the gains were uneven, and now describes a shift towards tariffs, subsidies and a more divided world.[1]
Capitalism does transform. But a transformation that leaves most people worse off is a decline with a new name.
Adam Smith did write of an “invisible hand”, but only in passing, a few times across his books. It was later economists who turned the phrase into a creed: that free markets, left alone, turn private self-interest into public benefit. Smith himself was warier. He noted that people of the same trade seldom meet together “but the conversation ends in a conspiracy against the public”.[2] If the hand keeps dealing the best cards to the same few people, it is stacking the deck. So yes, I think “late-stage” fits. Not because collapse is coming, but because the system has drifted from its purpose: making life better for nearly everyone, not just the few at the top.
Who holds the cards
Thomas Piketty’s work helps here. It doesn’t prove capitalism is ending. It shows that markets do not automatically produce a fair distribution of wealth: tax, inheritance, institutions, political bargaining and whether returns on capital outrun the growth of the wider economy all shape who owns what.[3] Capitalism can transform while inequality falls. It can also transform while inequality comes roaring back.
Percentages hide people, so here are the people. The richest tenth of American households, about 13.5 million of them, hold roughly 68 per cent of household wealth. The bottom half, about 67.5 million households, hold around 2.5 per cent.[4] The middle is shrinking too: 61 per cent of Americans were middle income in 1971, and 51 per cent by 2023.[5]
Federal Reserve Governor Lisa Cook calls this a “K-shaped” economy: better-off households keep spending while more vulnerable ones fall behind on their debts.[6]
Look at what holds up the top arm of that K. The ten largest companies now make up about 41 per cent of the value of America’s main share index, well above the peak of the dot-com bubble.[7] Most are AI and tech giants. AI spending now leads growth in US private investment,[8] yet these firms employ only a small fraction of American workers. The jobs are mostly elsewhere, in shops, hospitals, restaurants and offices, where hiring has slowed sharply.[9] The profits and share prices sit in one place; the jobs sit in another.
Spending has the same lopsided shape. By 2025 the richest tenth of earners accounted for nearly half of all consumer spending,[10] and much of their confidence rides on those share prices. The very rich also spend a smaller share of what they have, so an economy that funnels money upward slowly starves its own customers.
That is a very large bet on one horse. When a small lab released a cheap, capable model called DeepSeek in January 2025, the chipmaker Nvidia lost $593 billion of market value in a day.[11] If the AI giants are ever valued at what cheaper, open alternatives suggest they are worth, the weight of the economy falls back onto the ordinary firms that employ most people and are already hiring less. That is how a share-price correction could turn into mass unemployment and something like a second global financial crisis. The wealthy would lose fortunes they can afford. Everyone else would lose jobs and savings they can’t.
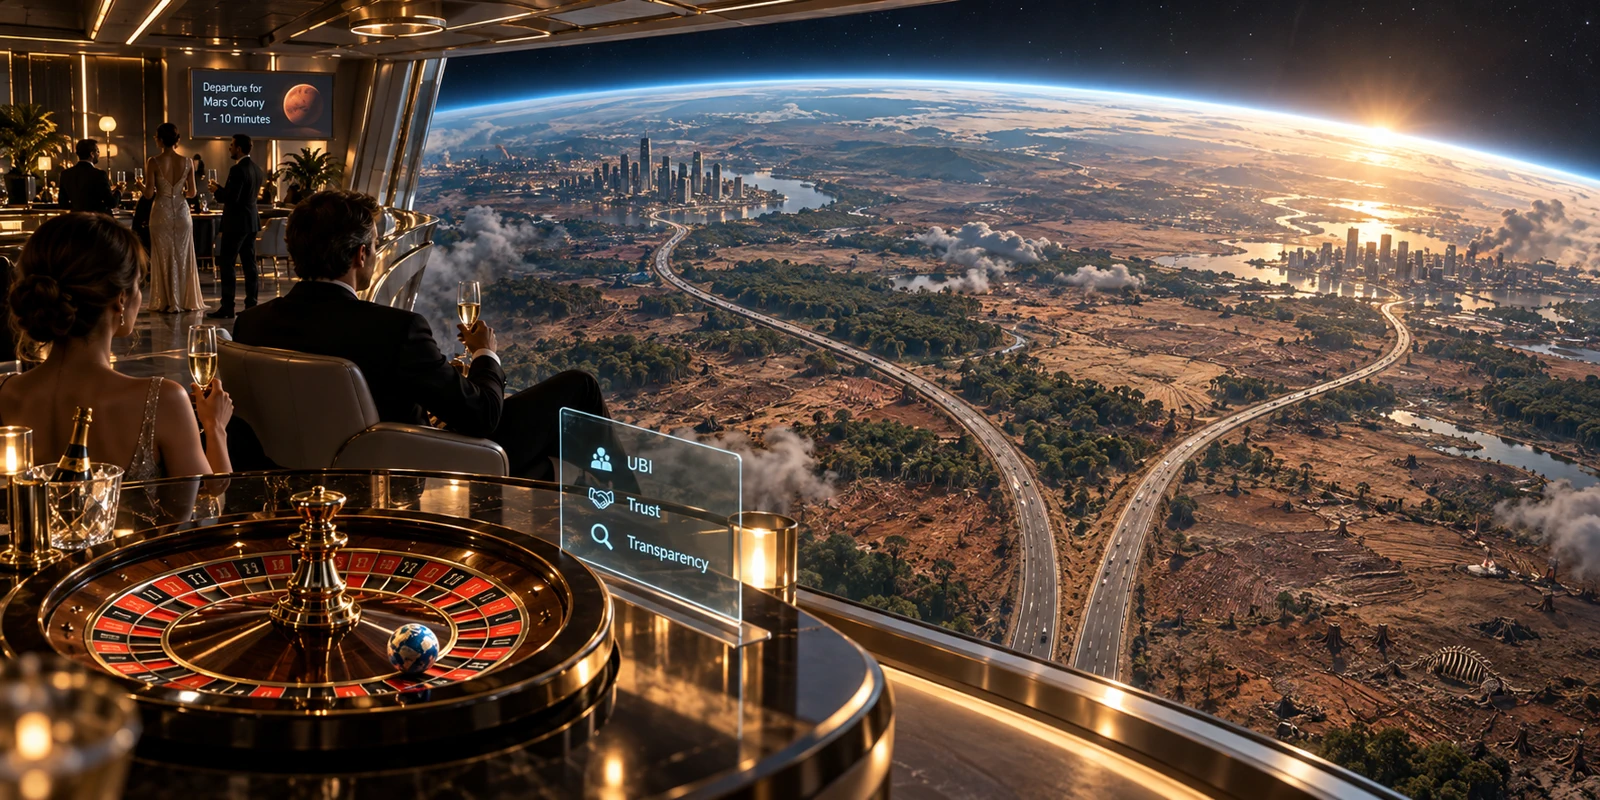
Transparent equals trust
Markets correct themselves only when the important information is visible. Sell a forest’s timber and GDP goes up, while the lost carbon, water and habitat barely register. The ledger is correct; the story is wrong.
Transparency isn’t trust, but trust is hard to build without it. Across 38 countries, the OECD found trust follows whether government seems open and fair; only 31 per cent of people felt they had a say.[12] In the United States, pollsters have asked the same question since 1958: how often do you trust the government in Washington to do what is right? Asking it unchanged for decades shows the long trend rather than one week’s mood. In 1958, 73 per cent said always or most of the time. By late 2025, 17 per cent did.[13]
When people are confused, or something they need is scarce, they shout, and politicians are glad to shout it back. Donald Trump is unusually good at it. Pew’s validated voter study, which checks what people say against official voting records, found that eligible people who skipped the 2020 election and voted in 2024 backed him 54 to 42.[14] He says aloud what people who had stopped voting say to each other, even when two of those things contradict. Whether policy follows is another matter. He didn’t create the trust problem; he is what a low-trust system produces.
Competition, not closeness to power, was meant to pick the winners. Yet this week the President and the heads of the biggest AI companies signed a voluntary safety accord he called “morally binding”, checked by auditors who report to the companies’ own boards.[15] Reassurance is not transparency. The same companies telling us AI is dangerous enough to need inspectors mostly keep their models closed, and I suspect one reason is that cheap, open models would show what the shares are really worth.
Late-stage communism
Communism offers the opposite cure: private wealth becomes private power, so hold the major assets in common, plan for need and share the gains. In theory, one owner and one plan, answerable to all, is its own kind of transparency.
It has transformed just as often. The Soviet command economy collapsed, and China went from Mao’s collective farms to Deng Xiaoping’s market reforms to today’s “socialist market economy”, complete with billionaires and, as it happens, DeepSeek. Equality hasn’t followed. China’s richest 10 per cent own about 68 per cent of its wealth, while the bottom half, more than half a billion adults, own about 6 per cent. Unlike America’s, though, China’s middle has grown fast, with hundreds of millions of people moving into the global middle class.[16] And there is an irony in its AI strategy: a one-party state giving away open models while Silicon Valley keeps most of its own locked up. If cheap open models become normal, the money flows back to whoever builds the chips, servers and data centres, and China intends to be one of them.
Here the transparency problem runs the other way. Power that few people can stop is also hard to question. Long-running Harvard surveys found genuine satisfaction with the central government,[17] yet presidential term limits are gone and censorship makes disagreement hard to see. “Late-stage communism” isn’t a real term; I’ve made it up. I mean a system that keeps changing form while its founding promise of fairness drifts out of reach.
Different roads, same place
Capitalism concentrates wealth until money shapes politics. Communism concentrates power until people can’t see inside. Step back and the result looks much the same. Of the world’s 8 billion or so people, about 5.6 billion are adults. The richest tenth of those adults, some 560 million people, own three-quarters of all wealth. The poorest half, about 2.8 billion adults, own 2 per cent.[16]
So what would help? Transparency, the trust it earns, and a fair floor under everyone.
A floor
A universal basic income is a modest, unconditional payment to everyone: enough for security, not enough to stop people working, building and trying again. I’m wary of a universal high income. If the owners of the machines paid everyone a generous allowance, ownership wouldn’t change; we would simply live on whatever they chose to hand down, which is capitalism transforming once more. A modest floor, run independently with a public formula, could be funded partly by a dividend from AI, which is built on centuries of shared human knowledge.
One possible option
The more speculative idea is what I call an Artificially Managed Economy. Not handing the economy to a chatbot, but an independent accounting layer that measures what our systems leave out: carbon, water, habitat, monopoly power, extreme wealth, and the interests of those who can’t sit at the table, from future generations and other species to, perhaps one day, AI itself.
It would only be worth having if it were completely open: open models, public goals, traceable data, rival models checking each other, independent audits and people able to change the rules. Otherwise whoever sets its goals could quietly steer society. It would also mean the very wealthy gradually giving up some power, through slow changes to tax and inheritance rather than confiscation.
I’m not claiming it’s the answer, and I’d like to hear better ones. My test for any system is simple. Can ordinary people see how it makes decisions, and can they challenge them? If not, it hasn’t earned our trust.
References
Links checked 1 October 2026.
| No. | Author and source | Year | Why this source matters | Link |
|---|---|---|---|---|
| 1 | World Trade Organization. World Trade Report 2026: Executive Summary. Geneva: WTO. | 2026 | The referee of global trade itself concedes the gains were uneven and describes the shift to tariffs, subsidies and fragmentation. | wto.org |
| 2 | Smith, A. An Inquiry into the Nature and Causes of the Wealth of Nations. London: W. Strahan and T. Cadell. | 1776 | The source of the “invisible hand” (used once, in Book IV) and of Smith’s warning about traders conspiring against the public (Book I). | gutenberg.org |
| 3 | Piketty, T. “Putting Distribution Back at the Center of Economics: Reflections on Capital in the Twenty-First Century”. Journal of Economic Perspectives 29(1). Nashville: American Economic Association. | 2015 | Piketty in his own words on why markets alone do not correct wealth concentration, and why institutions matter. | aeaweb.org |
| 4 | Board of Governors of the Federal Reserve System. Distributional Financial Accounts. Washington, DC: Federal Reserve. | 2026 | Official quarterly data on US wealth shares by percentile. In early 2026, the top 10 per cent held about 68 per cent and the bottom 50 per cent held about 2.5 per cent. | federalreserve.gov FRED series |
| 5 | Kochhar, R. The State of the American Middle Class. Washington, DC: Pew Research Center. | 2024 | Long-run measure of the shrinking US middle class, from 61 per cent of Americans in 1971 to 51 per cent in 2023. | pewresearch.org |
| 6 | Cook, L. D. Economic Outlook, speech to the Economic Club of Miami, 4 February. Washington, DC: Board of Governors of the Federal Reserve System. | 2026 | A sitting Fed governor describing the two-speed, K-shaped US economy. | federalreserve.gov |
| 7 | J.P. Morgan Asset Management. How Extreme Is Market Concentration?, On the Minds of Investors. New York: J.P. Morgan Asset Management. | 2026 | The ten largest stocks held about 41 per cent of S&P 500 value in May 2026, against 26.6 per cent at the dot-com peak. | am.jpmorgan.com |
| 8 | Epoch AI. The AI Boom Has Doubled Computing Infrastructure’s Share of US GDP. Online: Epoch AI. | 2026 | Shows AI infrastructure has become the leading driver of growth in US private investment. | epoch.ai |
| 9 | KPMG Economics. Payrolls Lose Altitude: September 2026 Employment Primer. New York: KPMG. | 2026 | Describes a low-hire US labour market with slowing payroll growth, weakest in healthcare, retail and hospitality. | kpmg.com |
| 10 | Marketplace, American Public Media. Nearly Half of U.S. Retail Spending Comes from Top 10% of Earners. St Paul, MN: American Public Media. | 2025 | Reports Moody’s Analytics finding that the top 10 per cent of earners drove nearly half of US consumer spending, a record since 1989. | marketplace.org |
| 11 | Reuters. DeepSeek Sparks AI Stock Selloff; Nvidia Posts Record Market-Cap Loss. London: Thomson Reuters, republished by The Dallas Morning News. | 2025 | Shows how quickly the American AI bet can be repriced when a cheaper model appears. | dallasnews.com |
| 12 | OECD. OECD Survey on Drivers of Trust in Public Institutions 2026 Results. Paris: OECD Publishing. | 2026 | Evidence from 38 countries that openness and fairness drive trust, and that few people feel they have a say. | oecd.org |
| 13 | Pew Research Center. Public Trust in Government: 1958-2025. Washington, DC: Pew Research Center. | 2025 | The longest-running trust question in US polling: 73 per cent in 1958 and 17 per cent in September 2025. | pewresearch.org |
| 14 | Pew Research Center. Voter Turnout, 2020-2024, validated voter study. Washington, DC: Pew Research Center. | 2025 | Matches survey answers to official voting records. People who did not vote in 2020 but voted in 2024 favoured Trump by 54 per cent to 42 per cent. | pewresearch.org |
| 15 | NBC News. After Summit with Tech Titans, Trump Calls for ‘Tremendous Self-Regulation’ by AI Companies. New York: NBC News. | 2026 | Report of this week’s voluntary AI accord, its board-reviewed auditing and the “morally binding” description. | nbcnews.com |
| 16 | World Inequality Lab. World Inequality Report 2026, China country sheet, global and regional wealth inequality. Paris: World Inequality Lab. | 2025 | China’s wealth shares, China’s rise into the global middle, and the global split: 560 million adults own 75 per cent and 2.8 billion own 2 per cent. | China sheet Global Regional |
| 17 | Cunningham, E., Saich, T. and Turiel, J. Understanding CCP Resilience: Surveying Chinese Public Opinion Through Time. Cambridge, MA: Ash Center, Harvard Kennedy School. | 2020 | Rare long-run independent survey finding genuine satisfaction with China’s central government. | ash.harvard.edu |
Comments
Anyone can read. Approved members can comment. or open the join page.
Your membership is waiting for approval. You can read the thread now.
If the box below shows Sign In, choose it, then Sign In with Froodx. Once is enough.